You’ve found a genuine edge. Your model disagrees with the market, the situational factors align, and you’re confident the number is off. Now comes the question that separates profitable bettors from talented bettors who still go broke: how much do you bet? Too little, and you’re leaving money on the table. Too much, and a bad run wipes you out before your edge has time to compound. The Kelly Criterion is the mathematical answer to this problem, and while it was originally developed for information theory in the 1950s by John L. Kelly Jr. at Bell Labs, it has become the gold standard for optimal bet sizing in any domain where you’re making repeated wagers with an identifiable edge.
The Kelly Criterion Formula Explained
The Kelly Criterion determines the fraction of your bankroll you should wager to maximize long-term growth. The formula for a simple two-outcome bet is:
f = (bp – q) / b
Where f is the fraction of your bankroll to bet, b is the decimal odds minus 1 (the net profit per dollar wagered), p is your estimated probability of winning, and q is the probability of losing (which is simply 1 – p).
Suppose you’re betting an NFL underdog at +150 (decimal odds of 2.50, so b = 1.50) and you estimate the team has a 45% chance of winning (p = 0.45, q = 0.55). Plugging in: f = (1.50 x 0.45 – 0.55) / 1.50 = (0.675 – 0.55) / 1.50 = 0.125 / 1.50 = 0.0833. Kelly says bet 8.33% of your bankroll.
Now consider a standard -110 spread bet where you estimate a 55% win probability. Here b = 0.909 (you risk $110 to win $100), p = 0.55, q = 0.45. The calculation: f = (0.909 x 0.55 – 0.45) / 0.909 = (0.50 – 0.45) / 0.909 = 0.055. Kelly recommends 5.5% of your bankroll. For a more typical edge — say 53% on a -110 bet — Kelly suggests about 1.3%. These numbers feel intuitively reasonable, which is one of the formula’s strengths: it scales your bet size to your edge, wagering more when your advantage is larger and less when it’s marginal.
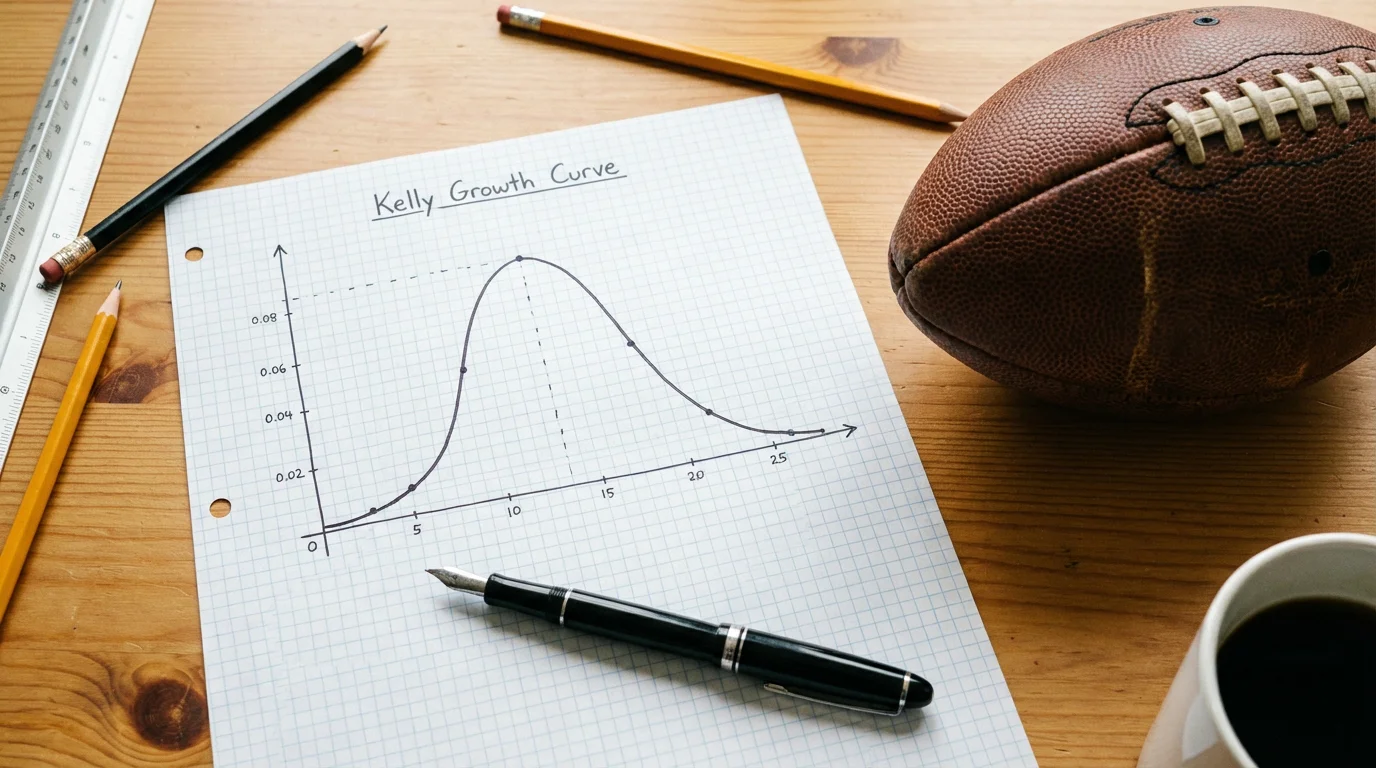
The mathematical elegance of Kelly is that it maximizes the geometric growth rate of your bankroll. In plain language, it grows your money as fast as possible without exposing you to unacceptable risk of ruin. Bet more than Kelly, and your bankroll’s expected growth rate actually decreases — even though each individual bet has a higher expected dollar return — because the increased variance creates a higher probability of catastrophic drawdowns. Bet less than Kelly, and you’re growing more slowly than you could, but with greater safety.
Why Full Kelly Is a Terrible Idea in Practice
On paper, Kelly is elegant. In practice, full Kelly staking in sports betting is reckless, and every serious bettor who has tried it has either abandoned it or gone broke. The reason comes down to a single uncomfortable truth: the Kelly formula assumes you know your exact edge, and in sports betting, you never do.
Your probability estimate — the p in the formula — is itself an estimate with uncertainty around it. If you think a team has a 55% chance of covering, your true confidence interval might be 50% to 60%. At 55%, Kelly says bet 5.5%. But if the true probability is actually 50%, the Kelly bet is zero — there’s no edge to exploit. And if it’s 48%, you’re actually betting the wrong side entirely. Full Kelly is optimal only when your probability inputs are perfectly calibrated, and no human being and no model achieves perfect calibration across hundreds of bets.
The practical consequences of estimation error under full Kelly are severe. Because the formula scales aggressively with perceived edge, even modest overestimation of your advantage leads to dramatic overbetting. A bettor who consistently overestimates their edge by 2% will bet roughly twice as much as they should, and the resulting bankroll volatility creates drawdowns deep enough to trigger emotional panic, strategy abandonment, or outright ruin. Full Kelly’s theoretical optimality dissolves the moment you introduce real-world uncertainty about your own accuracy.
The bankroll swings are also psychologically punishing. Full Kelly can produce drawdowns of 40% to 60% of your bankroll even when your model is working correctly, simply due to normal variance. Very few bettors — professional or recreational — can endure watching their bankroll cut in half and maintain the discipline to continue staking at the prescribed levels. The emotional pressure to reduce bets during a drawdown or increase them during a heater undermines the systematic approach that makes Kelly valuable in the first place.
Fractional Kelly: The Practical Compromise
The solution that virtually all professional bettors adopt is fractional Kelly — betting a fixed fraction of the full Kelly amount. The most common fraction is one-quarter to one-half Kelly, meaning if the formula recommends a 6% bet, you actually wager 1.5% to 3% of your bankroll. This dramatically reduces variance and drawdown risk while sacrificing only a modest amount of long-term growth.
The math behind fractional Kelly is favorable. Half Kelly produces approximately 75% of the growth rate of full Kelly while reducing the maximum expected drawdown by roughly half. Quarter Kelly produces about 50% of the growth rate with dramatically smaller swings. For a sports bettor with imperfect probability estimates — which is every sports bettor — the reduced variance of fractional Kelly more than compensates for the slower growth, because it keeps you in the game long enough for your edge to compound.
Fractional Kelly also provides a buffer against the estimation error problem. If you’re using half Kelly and your probability estimates are slightly overconfident, you end up betting roughly at the full Kelly level for your true edge — which is exactly right. If your estimates are accurate, you’re slightly underbet but still growing. The fractional approach turns a fragile optimal strategy into a robust one that performs reasonably well across a range of estimation accuracies, which is exactly what you want in an environment where you’re never certain how sharp your model really is.
The specific fraction you choose should reflect your confidence in your probability estimates. If you’re using a well-calibrated model with a multi-season track record, half Kelly is reasonable. If you’re working with a newer model or betting in markets where your edge is less certain, quarter Kelly provides more protection. Some professional bettors use a sliding scale — higher fractions for their highest-conviction plays and lower fractions for marginal spots — which adds another layer of nuance but also requires greater discipline and self-awareness.
Implementing Kelly in Your Football Betting
Putting fractional Kelly into practice requires three things: an honest assessment of your edge, a clearly defined bankroll, and the discipline to follow the formula even when it tells you to bet less than you want.
Start by establishing your bankroll as a separate, dedicated pool of money that you can afford to lose without affecting your daily life. Kelly-based staking only works when applied to a defined bankroll — if you’re pulling money in and out based on other financial needs, the mathematical framework breaks down. The bankroll is your operating capital, and the formula tells you how to deploy it.
Next, for each bet you’re considering, estimate your win probability and calculate the Kelly fraction using the formula above, then multiply by your chosen fraction (half, quarter, or whatever you’ve settled on). Record both the full Kelly amount and the fractional Kelly amount in your tracking spreadsheet. Over time, this data lets you evaluate whether your probability estimates were well-calibrated by comparing predicted win rates to actual win rates across different bet sizes.
One practical modification that many football bettors make is capping the maximum bet at 3% to 5% of their bankroll regardless of what the Kelly formula suggests. Even with fractional Kelly, there are occasional spots where the formula recommends a large bet — 7% or 8% of your bankroll on what appears to be a significant edge. In these cases, the cap prevents a single bad outcome from creating an outsized drawdown. It’s a concession to the reality that your biggest perceived edges are also the spots where your estimation error is most consequential.
Finally, update your bankroll figure regularly — ideally after every betting cycle (weekly for NFL, or after each Saturday slate for college football). Kelly is a dynamic system: as your bankroll grows, your bet sizes grow proportionally, and as it shrinks, your bets shrink to protect the remaining capital. This automatic scaling is one of Kelly’s greatest strengths — it accelerates compounding during winning periods and preserves capital during losing streaks without requiring you to make emotional decisions about when to bet more or less.
The Formula Doesn’t Care About Your Feelings
The Kelly Criterion offers something rare in sports betting: a mathematically grounded answer to a question that most bettors answer with their gut. How much should I bet? Not “whatever feels right.” Not “enough to make it exciting.” Not “more than last time because I’m on a hot streak.” The formula takes your edge and your odds, runs the math, and gives you a number. That number might be boring — 1.8% of your bankroll isn’t going to generate cocktail-party stories — but boring compounds. Exciting goes broke. The bettors who last long enough to see their edge pay off are the ones who trusted the formula when their instincts screamed to do something different.
