You can have the sharpest analytical mind in football betting and still go broke. It happens all the time. A bettor with a genuine 55% win rate on spreads blows up their bankroll because they sized one bad week too aggressively and never recovered. The analysis was sound. The money management was not. Bankroll management is the unsexy foundation that determines whether a skilled bettor survives long enough to realize their edge or flames out in a spectacular display of overconfidence.
This guide covers the full system: defining your bankroll, calculating unit sizes, choosing a staking method, adjusting dynamically across a season, understanding risk of ruin, and setting mechanical loss limits that protect you from your own worst impulses.
Advanced bettors often rely on the Kelly Criterion for optimal bet sizing to maximize growth while minimizing the risk of ruin.
Defining Your Allocatable Betting Bankroll
Your bankroll is a fixed sum of money set aside exclusively for betting. It is not your savings account. It is not next month’s rent. It is not the balance of your checking account minus estimated expenses. Your bankroll is money that, if it disappeared entirely tomorrow, would not change your life in any material way.
This is not a suggestion. It is the single most important rule in sports betting money management. Every staking system, every risk calculation, and every loss limit described in this article assumes that your bankroll is completely separate from your living expenses. If you skip this step and bet with money you cannot afford to lose, no staking system will save you. The emotional pressure of betting with essential funds distorts your decision-making in ways that are invisible in the moment and catastrophic over time.
A reasonable starting bankroll for a recreational bettor is an amount you would be comfortable spending on a season’s worth of entertainment. For some people that is $500. For others it is $5,000. The specific number matters less than the psychological separation. Once you deposit that money into your sportsbook accounts, mentally classify it as spent. If you get it back with profit, that is a bonus. If you lose it, you had a season of entertainment and education.
Units: The Universal Language of Bet Sizing
A unit is a standardized bet size expressed as a percentage of your bankroll. If your bankroll is $2,000 and your unit size is 2%, one unit equals $40. Every bet you place is denominated in units rather than dollars, which serves two purposes: it standardizes your risk per bet regardless of bankroll size, and it provides a common language for discussing and tracking results.
The standard recommendation for unit size is 1-3% of your bankroll. A 1% unit is conservative and minimizes the chance of a catastrophic drawdown. A 3% unit is moderately aggressive and amplifies both gains and losses. Going above 5% per bet exposes you to risk of ruin levels that are uncomfortable for any bettor who intends to stay solvent across a full season.
The reason for small unit sizes is mathematical, not philosophical. Even a skilled bettor with a 55% win rate on -110 bets will experience losing streaks of 8, 10, or even 12 bets in a row over the course of a season. At 1% per unit, a 12-bet losing streak costs 12% of the bankroll. Painful but survivable. At 5% per unit, the same streak costs 60% of the bankroll, and the psychological pressure to chase losses or increase stakes to recover becomes nearly irresistible. At 10% per unit, the streak wipes out the bankroll and there is nothing left to manage.
Flat Staking vs. Variable Staking
Flat staking means betting the same unit size on every wager regardless of your confidence level. If your unit is $40, every bet is $40. The Monday night game you love and the Thursday afternoon college game you merely like both get the same $40.
Variable staking means adjusting your bet size based on perceived edge. A bet you consider a strong play might get 2 or 3 units, while a marginal play gets 1 unit. This approach theoretically optimizes returns by concentrating more capital on your highest-confidence picks.
In practice, flat staking is the better choice for the vast majority of bettors. The reason is that most bettors are poor judges of their own confidence levels. Studies of betting behavior consistently show that bettors’ self-reported confidence correlates weakly with actual outcomes. The games you feel strongest about are not reliably your most profitable games. They are often the games where you have the most emotional investment, which is a different thing entirely.
Flat staking removes this vulnerability. It forces discipline by preventing you from over-sizing on games where your conviction is high but your edge may not be. It also simplifies tracking and analysis. When every bet is the same size, your win rate translates directly to your ROI without needing to weight by stake size. This transparency makes it easier to identify whether your edge is real.
Dynamic Bankroll Adjustment: Recalculating as You Go
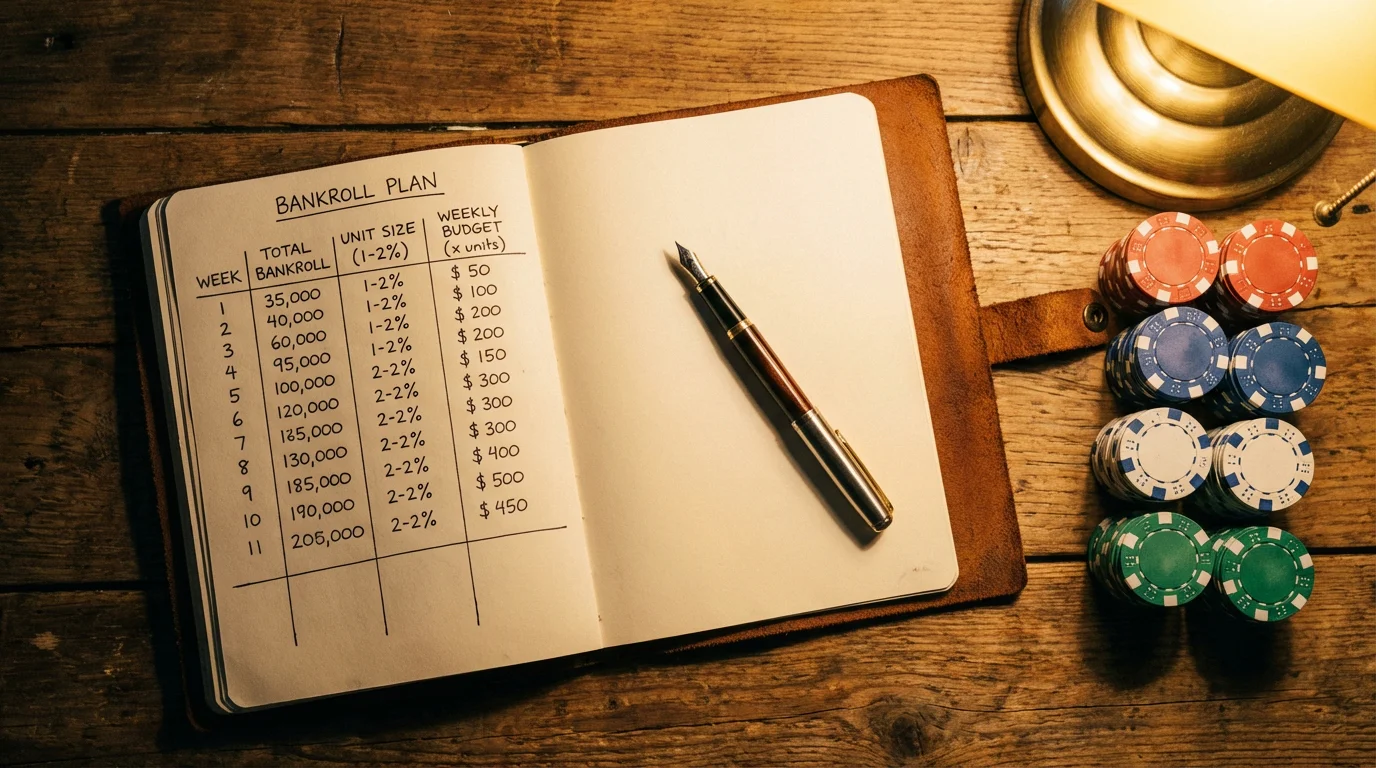
Your bankroll is not a static number. It changes with every bet. If you start the season with $2,000 and your unit is 2% ($40), what happens when your bankroll grows to $2,800 after a hot October? And what happens when it drops to $1,400 after a rough November?
Dynamic bankroll adjustment means recalculating your unit size periodically based on your current bankroll. If you recalculate weekly and your bankroll has grown to $2,800, your new unit is $56. If it has dropped to $1,400, your new unit is $28. This approach increases your bet size when you are winning and decreases it when you are losing, which mathematically optimizes the growth rate of your bankroll while simultaneously reducing the risk of ruin during drawdowns.
The recalculation frequency matters. Recalculating after every bet is impractical and creates whiplash in your stake sizes. Recalculating monthly is too slow to respond to significant bankroll swings during a football season. The sweet spot for most bettors is weekly recalculation, aligned with the natural rhythm of the NFL and college football schedule. Every Monday, review your bankroll balance, recalculate your unit, and use that unit for the coming week’s bets.
One important psychological note: dynamic bankroll adjustment requires you to reduce your bet size after losing periods. This is the opposite of what your brain wants to do. After a losing week, the impulse is to increase stakes to recover faster. Dynamic adjustment says no, bet smaller, because your bankroll is smaller and the same percentage of a smaller number is a smaller dollar amount. Following this rule during drawdowns is one of the hardest disciplines in sports betting, and it is also one of the most important.
Risk of Ruin: The Math of Survival
Risk of ruin is the probability that your bankroll will be completely depleted before you can recover. It is a function of three variables: your edge (win rate above breakeven), your unit size (stake as a percentage of bankroll), and the variance of your bet outcomes.
For a bettor with a 54% win rate on -110 bets using 2% unit sizing, the risk of ruin over a full season is extremely low, well below 1%. For the same bettor using 10% unit sizing, the risk of ruin jumps to roughly 20-30%. The edge is identical. The only thing that changed is the stake size, and it transformed a nearly indestructible bankroll into one that has a meaningful chance of complete elimination.
The risk of ruin calculation also reveals a counterintuitive truth: even bettors with a genuine edge can go broke if they overbet. A 56% win rate is elite-level performance in NFL spread betting, but at 15% unit sizing, the risk of ruin is still substantial because the variance of individual bet outcomes is high enough to produce devastating losing streaks before the edge has time to assert itself.
The practical takeaway is that unit sizing should be determined by your risk tolerance and your confidence in the durability of your edge, not by your desire for fast growth. A 1-2% unit size gives your edge room to compound over months and years. A 5%+ unit size gambles that your edge is large enough to overcome the variance before a losing streak destroys the bankroll. Most bettors overestimate both their edge and their tolerance for drawdowns, which means most bettors should bet smaller than they think they should.
Mechanical Loss Limits: Rules That Protect You From Yourself
A loss limit is a pre-defined rule that stops you from betting once you have lost a certain amount within a specified period. Common structures include daily loss limits (stop after losing 3 units in a day), weekly loss limits (stop after losing 7 units in a week), and session loss limits (stop after losing 5 units in a single sitting).
Loss limits exist because human decision-making degrades under financial stress. After three consecutive losses on a Sunday slate, your analytical quality drops. You are more likely to chase, more likely to size up, and more likely to bet a game you have not properly evaluated. The loss limit removes you from the market before this degradation reaches a critical point.
The specific numbers in your loss limits should reflect your unit size and your typical betting volume. A bettor who places 5-8 bets per week might set a weekly loss limit of 5 units. A bettor who places 15-20 bets per week might set a higher absolute limit but a similar percentage of their typical weekly action. The goal is to stop the bleeding during abnormally bad stretches without cutting off your activity during normal variance.
Critically, loss limits must be non-negotiable. If your rule says stop at 5 units of loss for the week, you stop. You do not make an exception for the Monday night game that you think is the best play of the week. You do not rationalize that the early losses were bad luck and the late games are different. The limit is the limit. If you cannot follow it, no amount of analytical skill will save your bankroll over the long term.
The Bankroll as a Business Account
The most useful mental model for bankroll management is to treat your betting bankroll like a small business account. A business does not invest its entire budget into a single product launch. It allocates a fixed percentage of capital per project, reserves an emergency fund, and reviews its financial position at regular intervals. It has policies for when to invest more aggressively and when to pull back.
Your bankroll deserves the same discipline. Allocate a fixed percentage per bet. Reserve a portion of your bankroll as a buffer that you never touch for individual wagers. Review your financial position weekly. Have explicit rules for scaling up when the bankroll grows and scaling down when it shrinks. Document these rules before the season starts, when your judgment is not clouded by recent results.
The bettors who survive long enough to profit are not always the ones with the best picks. They are the ones whose bankroll management allowed them to stay in the game through inevitable losing stretches. A 55% win rate is meaningless if your bankroll is gone by Week 8. The edge only works if the bankroll endures long enough to let it work. Everything in this article exists to ensure that it does.
Elevate your handicapping skills by following the proven systems at Betting Football Online.
